
How Long Do Insurance Claims Take? Realistic Timelines
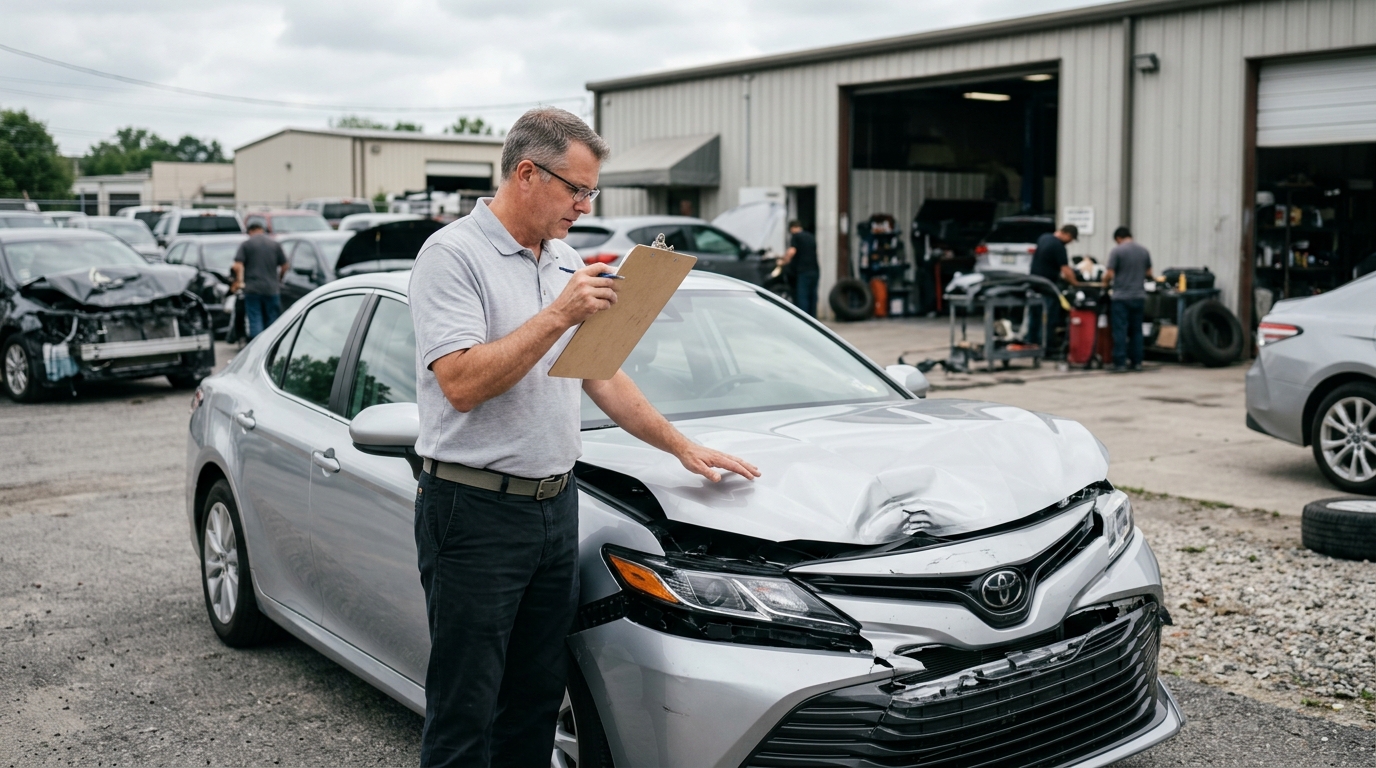
The straight answer to how long do insurance claims take is that it varies. A simple fender-bender with obvious liability can be finished in two to four weeks, while a serious injury or a fight over fault can run past a year. Below are realistic timelines for property damage, bodily injury, and total loss files, along with what accelerates a claim and what grinds one to a halt.
In this article
The Four Things That Set a Claim's Pace
Every claim travels the same basic pipeline: report, investigation, evaluation, settlement, payment. The only thing that shifts is how long each stage runs. Four variables drive the pace more than anything else.
Complexity comes first. One car, one driver, one witness, and a crumpled bumper is nothing like a four-vehicle pileup with disputed fault and three injured passengers. Clarity of liability is second. Where fault is obvious - a rear-end hit, a red light captured on video - carriers move fast. A contested liability file triggers investigation delays that can add 30 to 90 days by themselves.
Third comes the kind of loss. Property damage is mostly arithmetic: estimate, repair, pay. Injury claims follow the medical treatment, and no carrier settles before doctors can describe the long-term picture. Fourth is state law. Each state's fair claim settlement practices statute imposes minimum deadlines for acknowledgment, investigation, and payment. Adjusters have those dates memorized and schedule their files around them.
Cooperation counts as well. People who return calls and forward paperwork within 24 hours frequently settle weeks sooner than those who let it sit.
How Fast Property Damage Claims Close
Property damage files - crumpled metal, shattered glass, stolen vehicles - close faster than anything else. Knowing how long do insurance claims take for everyday vehicle damage keeps expectations grounded:
- Glass-only claims (windshield, side windows): 3 to 7 days. Most carriers bill directly through Safelite or a local shop, so no adjuster has to look at the car.
- Minor collision with clear fault: 2 to 4 weeks from the filing to a check or a finished repair.
- Moderate collision needing an inspection: 3 to 6 weeks. Getting an adjuster out normally adds 5 to 10 business days.
- Comprehensive losses (hail, theft, vandalism): 2 to 6 weeks, with theft claims slowed by police report requirements.
- Collisions with disputed liability: 30 to 90 days at minimum while adjusters take recorded statements, pull the police report, and occasionally reconstruct the crash.
- Hit-and-run claims: 4 to 8 weeks. Uninsured motorist coverage responds, but carriers investigate closely to screen out fraud.
Direct repair program shops - the body shops partnered with your carrier - typically shave two to five business days off these timelines, since the estimate gets written on site.
Why Injury Claims Take So Much Longer
Injury claims run on an entirely different clock. No carrier settles one until the injured person hits maximum medical improvement - the stage where doctors can put in writing how much recovery is realistic and which limitations are permanent. Skip ahead of that point and the settlement will not stretch to cover future care.
Soft-tissue injuries such as whiplash or minor sprains put that milestone three to six months out from the crash. A concussion that heals cleanly might close in four to nine months. Surgical fractures, spinal injuries, and traumatic brain injuries routinely need 12 to 24 months. Files involving permanent disability, wrongful death, or long-term pain management reach two or three years, particularly once a suit is filed.
First-party injury claims - medical payments coverage or personal injury protection on the claimant's own policy - close quicker than third-party claims against another driver's carrier, because nobody is negotiating against you. Third-party files bring demand letters, counteroffers, and frequently mediation. Bringing in an attorney generally adds two to four months but lifts settlements substantially, especially where liability is clear and injuries are documented.
Ready to compare car insurance rates?
See quotes from top insurers side by side. Free, about two minutes, no obligation.
Get My Quotes →Total Loss Files Run on Their Own Schedule
Once a vehicle is written off, the claim stops being about repairs and becomes about valuation. Plan on four to eight weeks from crash to payment, moving through these stages:
- Inspection and damage estimate - 3 to 7 business days. An adjuster or independent appraiser looks the vehicle over in person or works from photos.
- Total loss decision - 1 to 3 business days. The car is totaled if repair costs plus salvage value pass roughly 70 to 80 percent of actual cash value, with thresholds varying by state and insurer.
- Actual Cash Value figured and offered - 3 to 10 business days. Carriers lean on valuation tools such as CCC ONE or Mitchell to weigh recent local sales.
- Negotiation and sign-off - 1 to 14 days. Owners can challenge the ACV offer using comparable listings, dealer quotes, or an independent appraisal.
- Title work and lienholder payoff - 5 to 14 days. On a financed car the lender has to sign before any money moves.
- Payment released - 1 to 7 days after the title clears.
Anyone who owes more than the car is worth needs gap insurance to close that hole; without it the loan balance keeps building while the paperwork crawls.
The State Deadlines Insurers Have to Meet
Every state enforces a fair claim settlement practices act that imposes firm response deadlines on carriers. Those laws cannot guarantee a quick settlement, but they do stop outright stonewalling. A sample of how the windows look:
Texas requires carriers to acknowledge a claim within 15 business days and to accept or deny it within 15 business days of getting the necessary proof. California wants acknowledgment inside 15 calendar days, with the coverage decision due in 40 days. Florida generally allows 90 days for payment once a claim is confirmed. New York requires acknowledgment within 15 business days plus status updates every 90 days while a claim stays open.
Blowing those deadlines opens carriers to bad faith claims - standalone lawsuits capable of producing punitive damages far above the underlying policy limits. That is why adjusters know precisely how long do insurance claims take under their own state's statutes and almost never let a date slide without written justification tied to a specific investigative step.
What Drags a Claim Out
Certain delays cannot be helped. Others trace back to claimant mistakes that pile on weeks. The usual culprits:
- Disputed liability where driver accounts conflict and no neutral witness exists
- A missing or slow police report - some jurisdictions need 5 to 15 business days to release one
- Breaks in medical treatment that give carriers room to argue the injuries came from somewhere else
- Claimants who take days to call back or return signed forms
- Multi-vehicle crashes where three or more carriers have to coordinate on liability
- Suspected fraud sending the file to a special investigation unit, which usually adds 30 to 120 days
- An uninsured or underinsured motorist in the mix, requiring additional coverage verification
- Catastrophes such as hurricanes or hail storms that bury adjusters under thousands of claims at once
Practical Ways to Speed Your Claim Up
Claimants steer the timeline more than they think. Report within 24 to 48 hours of the crash - sitting on it for weeks hands the carrier a reason to question the story. At the scene, photograph where the vehicles came to rest before anything gets moved, the damage from several angles, plates, insurance cards, driver's licenses, and any visible injuries. Grab the police report number before you leave.
Answer every adjuster call and document request inside one business day. Missing paperwork causes more avoidable delay than anything else. If the carrier's repair estimate looks thin, bring in two independent body shop estimates - most states require the insurer to weigh them before finalizing an offer.
On injury claims, attend every prescribed appointment and therapy session. Gaps in treatment are exactly what defense attorneys and adjusters use to cut a settlement down. Keep a mileage log for medical trips plus copies of every bill and Explanation of Benefits.
Learn your state's fair claim settlement deadlines and name them in writing whenever an adjuster starts dragging. A polite statute citation in an email has a way of moving a file to the top of the stack.
Frequently Asked Questions
What deadline does an insurer face on a car accident claim?
Each state's fair claim settlement act sets floors - commonly 15 to 40 days to acknowledge and 30 to 90 days to accept or deny after proof of loss arrives. No universal deadline governs the actual payment, though most states expect confirmed claims to close within a reasonable period, often described as 30 to 90 days from acceptance. Missing those windows without written justification invites a bad faith claim.
Why has my car insurance claim stalled out for so long?
Usual explanations are contested liability, paperwork that never arrived, medical treatment that has not stabilized, or adjusters buried after a regional catastrophe like a hail storm. Fraud reviews and coordination among several carriers on a multi-vehicle crash can add 30 to 120 days on top of a normal schedule. A weekly call asking for a written status update usually reveals the specific holdup and restarts movement.
When do injury claims usually settle?
Soft-tissue cases generally settle three to six months after the crash, once treatment wraps up. Injuries needing surgery or extended physical therapy commonly run 12 to 24 months, because carriers wait for documented maximum medical improvement. Permanent disability cases and those that turn into lawsuits often stretch two or three years, though that wait usually buys a materially larger settlement.
Is suing an option when a claim drags on?
Yes. Every state allows bad faith actions against carriers that unreasonably delay, deny, or lowball a settlement. A bad faith suit can win back the original claim along with attorney fees, plus punitive damages or a multiplier on the delayed benefit in many states. Most policyholders begin with a complaint to the state department of insurance, which frequently gets a stalled file moving inside a week or two.
Ready to compare car insurance rates?
See quotes from top insurers side by side. Free, about two minutes, no obligation.
Get My Quotes →