
What Does Comprehensive Insurance Cover? The 12 Perils
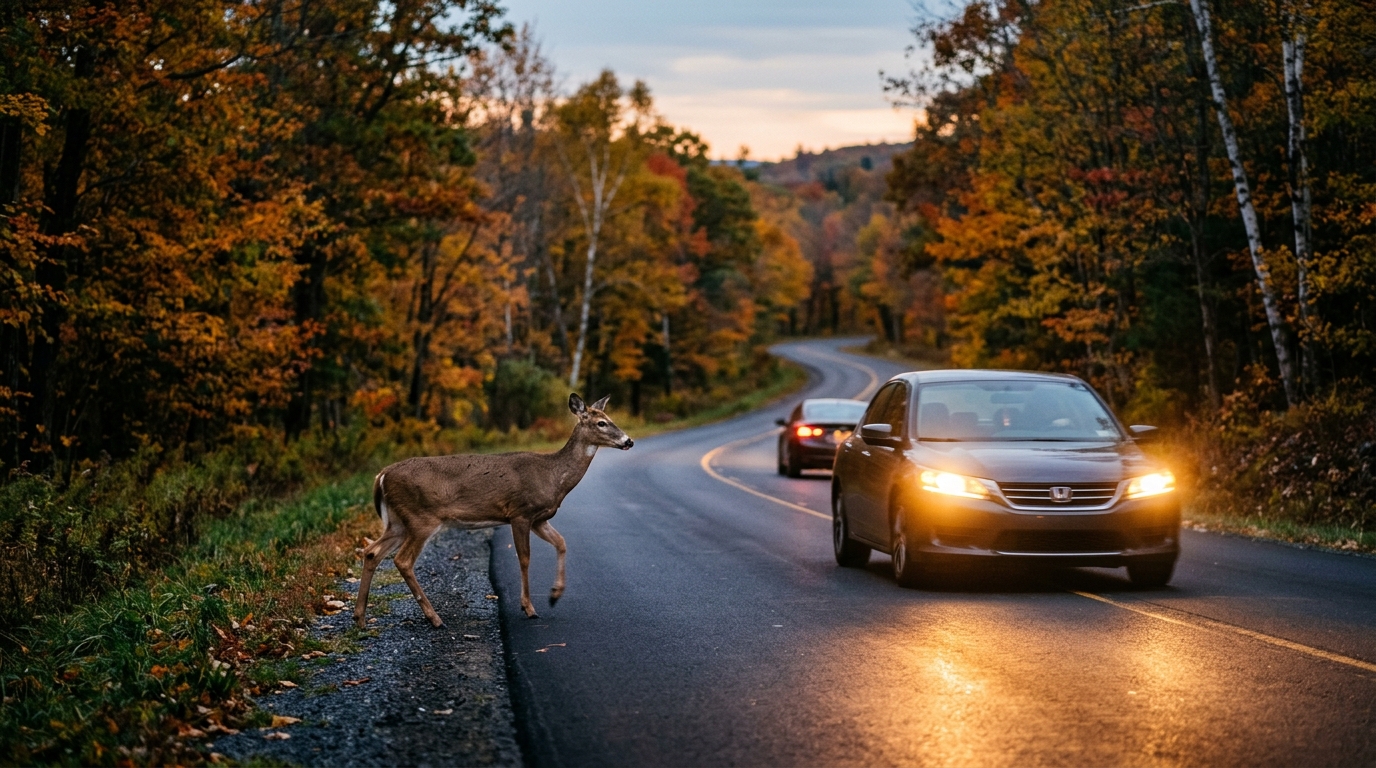
Most drivers treat comprehensive insurance as a blanket that catches anything bad happening to the car — and it is not that, which is exactly why the question deserves a real answer. Comprehensive is a tightly drawn category built around non-collision events, and misjudging where that boundary sits is how people wind up paying cash for damage they were certain was protected. Below is precisely what sits inside the definition, what sits outside it, and why one particular deer scenario confuses roughly 40% of the drivers who file it.
In this article
Comprehensive vs. Collision: Where the Line Sits
Physical damage to your car gets divided by insurers into two distinct coverages. Collision pays when your vehicle strikes something — another car, a guardrail, a pothole, a mailbox. Comprehensive picks up nearly everything else that can wreck a car, parked or moving, without an impact against another vehicle or a fixed object you steered into. On the declarations page some carriers print it as other than collision (OTC) coverage.
No state's minimum liability law requires either one, though a lender financing or leasing the car will nearly always demand both until the balance is cleared. Drivers asking what does comprehensive insurance cover are usually caught off guard to find it is a specific enumerated list of perils and not a general safety net. A peril that is not named in the policy wording is not covered, however much it feels like it ought to be. Helpfully, that list barely shifts across GEICO, State Farm, Progressive, Allstate, USAA, and Liberty Mutual, so coverage in Ohio looks very much like coverage in Arizona.
The 12 Non-Collision Perils on the Covered List
All the major carriers build comprehensive around more or less the same twelve buckets. Wording varies company to company, but the events themselves stay put:
- The whole car stolen — taken outright, recovered later or never
- Theft of permanently attached parts — catalytic converters, wheels, factory stereos, tailgates
- Vandalism — keyed doors, slashed tires, spray paint, smashed side windows
- Fire — under-hood fires, garage fires, wildfire damage whether parked or on the move
- Explosion — rare, yet named in the policy
- Falling objects — tree limbs, ice off an overpass, cargo tumbling from another vehicle
- Hail — the costliest comprehensive peril of all in Texas, Colorado, and Nebraska
- Windstorm, hurricane, or tornado — debris driven by wind plus structural damage
- Flood and rising water — hydro-locked engines from driving into standing water included
- Earthquake — commonly included with no separate premium line
- Riot, civil disturbance, or vandalism amid unrest
- Striking an animal — deer, bear, raccoon, livestock, birds
The Deer Rule Almost Nobody Sees Coming
Animal strikes generate more confusion than any other comprehensive claim. When a deer bolts into the road and your car connects with it, the damage falls under comprehensive rather than collision — even though colliding is exactly what happened. Roughly 40% of drivers guess the other way because of the label, and that mistake hurts them twice. To begin with, the comprehensive deductible on a given policy is frequently lower than the collision deductible, so filing under the wrong heading costs you more cash. On top of that, comprehensive claims usually do not bump a driver into a higher at-fault risk tier the way collision claims will.
State Farm on its own handles well over a million animal-related claims annually, and the danger spikes hard from October through December during rut season. One exception deserves attention: a driver who swerves away from a deer and strikes a tree, a guardrail, or oncoming traffic has a collision claim, since the real impact was with a fixed object. What decides it is the thing the car actually hit, not whatever made the driver react.
Ready to compare car insurance rates?
See quotes from top insurers side by side. Free, about two minutes, no obligation.
Get My Quotes →The Exclusions Comprehensive Spells Out
Even a top-tier comprehensive policy shuts out entire categories. These exclusions drive the bulk of denied claims:
- Damage from striking another vehicle — collision territory, without exception
- Mechanical failure and normal wear — blown engines, transmission trouble, worn-out brakes
- Personal property inside the car — a laptop or phone taken off the seat is a renters or homeowners claim
- Custom parts and equipment past the built-in cap — generally $1,000 to $1,500 without a separate endorsement
- Aftermarket modifications never declared on the policy
- Deliberate damage done by the driver or someone in the household
- Racing, track days, and off-road events
- Rideshare or delivery driving, absent added rideshare coverage
- Hauling commercial cargo on a personal auto policy
On that list, aftermarket wheels, lift kits, and upgraded stereo systems produce more denials than anything else. Modify a vehicle and the changes have to be declared and endorsed onto the policy, or the settlement gets calculated on the factory equivalent instead.
The Price of Comprehensive and When to Drop It
Comprehensive is among the least expensive pieces of an auto policy. The national norm falls around $150 to $250 per year, though that spread widens a lot depending on state, what the car is worth, the deductible you pick, and how often claims get filed locally. In hail country — Texas, Colorado, Oklahoma, Nebraska — $400 or more is routine, while drivers in calmer states such as Vermont, Maine, or Ohio frequently come in well under $150.
The standard deductible steps are $250, $500, and $1,000. Moving from $250 up to a $1,000 deductible usually trims 20% to 40% off the comprehensive slice of the premium — often enough to earn back the extra risk inside two or three claim-free years. Whether the coverage is worth carrying at all comes down to the car's actual cash value. A serviceable rule: when the yearly comprehensive premium and the deductible together pass roughly 10% of the vehicle's worth, it is at least time to think about dropping it. On a 12-year-old sedan booking at $3,500, that calculation usually argues for liability-only.
What Filing a Comprehensive Claim Looks Like
These claims typically settle quicker than collision claims, since nobody is arguing over fault and no second driver is in the mix. The order of operations barely changes between carriers:
- Photograph the damage before the car gets moved, assuming it is safe to do so
- Get a police report on file for theft, vandalism, or anything your state mandates — a number of states require one for animal strikes past a damage threshold
- Report it to the insurer, generally in the app; most carriers open a new claim in under five minutes
- Supply a repair estimate — plenty of insurers now inspect remotely from uploaded photos instead of dispatching an adjuster
- Cover the deductible; the carrier pays the rest up to the vehicle's actual cash value
A total loss takes a different route. The carrier pays actual cash value less the deductible and takes the title. When a loan is still outstanding, the check goes to the lender first, and whatever gap remains between the ACV and the loan balance lands on the borrower unless gap insurance is in force. One or two comprehensive claims generally will not push a driver into a higher rate tier, but a steady pattern of them — multiple theft losses especially — eventually raises premiums or brings a non-renewal notice.
Frequently Asked Questions
Does hitting a deer fall under comprehensive or collision?
Striking an animal — a deer, a bear, livestock, even a bird — files as a comprehensive claim rather than a collision one, despite "collision" being the plain description of the event. In practice that means the lower deductible applies and the incident is not recorded as at-fault. The exception comes when you swerve away from the animal and hit a tree or another car, which turns it into a collision claim because the real impact was with a fixed object.
Is a cracked windshield a comprehensive claim?
Yes. Glass broken by rocks, road debris, hail, or vandalism sits squarely inside comprehensive. A few states — Florida, Kentucky, and South Carolina among them — force insurers to waive the deductible outright on windshield repair, and most large carriers waive it nationwide for repairs, though not full replacements, provided the crack is still small enough to fix.
How is comprehensive different from full coverage?
"Full coverage" is not a product anyone can buy — it is casual shorthand for a policy carrying liability, collision, and comprehensive at the same time. Comprehensive is one of the three pieces inside that bundle. Technically a policy can hold collision without comprehensive or the reverse, though lenders and leasing companies nearly always insist on both while a loan or lease is open.
Should I drop comprehensive on an aging car?
Frequently, yes. The familiar guideline says to weigh dropping it once the annual premium plus the deductible clears roughly 10% of the car's actual cash value. Take a vehicle worth $3,000 carrying a $500 deductible and a $250 annual premium: across a few years the coverage returns barely more than the owner pays in. Drivers parked in high-hail or high-theft areas often hang on to it longer.
Will comprehensive pay for flood damage?
Yes. Flood and rising water appear by name in the comprehensive peril list, whether the car sits in a driveway through a hurricane or gets swept up by a flash flood mid-drive. That is among the best reasons to keep comprehensive on anything stored in a flood-prone area, because one waterlogged engine is usually enough to write off the whole car.
What is the monthly cost of comprehensive coverage?
The national average sits near $13 to $21 per month, running from below $10 in low-risk states up past $35 where hail is constant, like Texas, Colorado, and Nebraska. Pushing the deductible from $250 to $1,000 normally cuts the monthly figure by 20% to 40%. Vehicle value, ZIP code, and driving history each move it as well.
Ready to compare car insurance rates?
See quotes from top insurers side by side. Free, about two minutes, no obligation.
Get My Quotes →