
Rental Car Reimbursement Coverage: Worth Adding or Not?
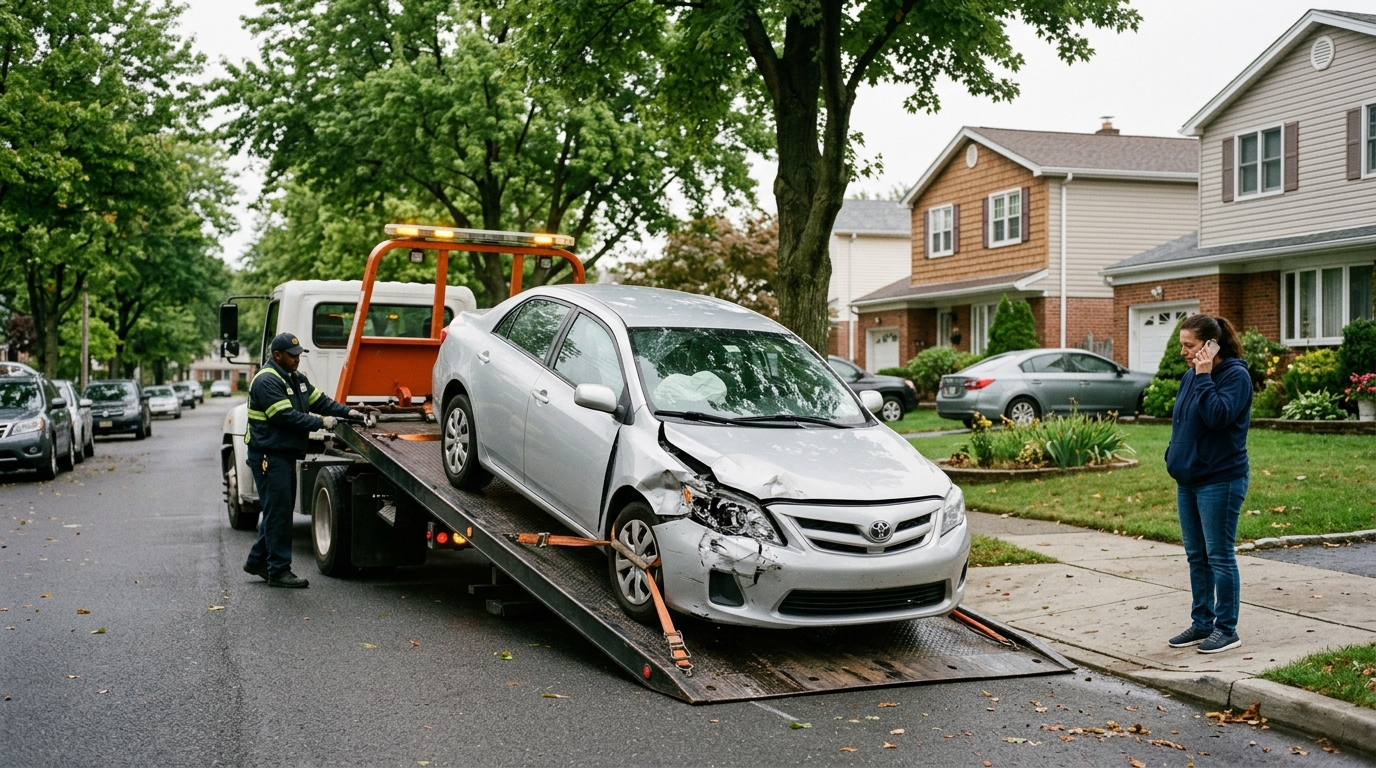
Rental car reimbursement coverage is an optional endorsement that funds a temporary vehicle while a covered car sits in the repair shop. The price usually lands between $2 and $8 per month, yet daily caps and exclusions decide whether the coverage actually delivers once a claim is filed. What follows covers what the endorsement includes, the fine print that leaves people paying at the rental counter, and less expensive ways to close the same gap.
In this article
What the Coverage Actually Funds
This is a first-party coverage on an auto policy, and it pays for a stand-in vehicle while the insured car is being repaired after a covered claim. It only switches on with an open collision or comprehensive claim behind it — someone rear-ends you, a branch comes through the hood, a catalytic converter disappears. Mechanical failures, scheduled maintenance, and dead batteries all sit outside it, and so does a trip to the dealer for recall work.
The clock generally starts the day the car goes into the shop and stops the day the work is finished. Nothing pays the counter deposit, the damage waiver the rental company pitches, or an upgrade to something bigger. Rent a $75-per-day SUV on a $40 daily limit and the remaining $35 comes out of your own pocket every single day.
It is also a different product from the rental car insurance sold at the airport counter, which protects a vehicle a driver is renting while traveling. Mixing the two up costs households actual money year after year.
The Caps That Catch Drivers Off Guard
Disappointment almost always traces back to the fine print. Five limits decide how much money actually comes back:
- The daily payout. Policies default to $30-$50 a day in most cases. Across US cities in 2026, a midsize SUV goes for $60-$90 while a full-size truck regularly asks $100+ daily.
- The per-claim ceiling. Almost every policy stops total reimbursement at $900, $1,200, or $1,500 for a single claim. Thirty days sitting at a body shop at $50 a day runs into the $1,500 ceiling and quits.
- Repair time only. Payment ends the day the work is done, not the day you collect the car, so weekends and scheduling gaps go unfunded.
- Total-loss cutoffs. Once a car is declared a total loss, most carriers fund the rental only until the settlement offer arrives, usually 3 to 7 days past the appraisal. Whatever time it takes to find a replacement is yours to cover.
- Fees that never qualify. Taxes, airport surcharges, extra-driver charges, tolls, and the loss damage waiver pushed at the counter all come out of pocket.
Weighing the Premium Against the Payout
As endorsements go, this is one of the least expensive on any auto policy. Figure $2 to $8 monthly per car, which works out to $24 to $96 a year. Raising the daily limit or the total cap moves the price up through predictable tiers.
How the math lands depends on the driver. A middling collision repair — bumper, quarter panel, sensor recalibration — averages 10 to 21 days in the shop, and backordered parts can stretch that beyond 45 days on newer cars full of electronic control modules. Take a $40-per-day policy with a $1,200 cap costing $60 a year: a single 20-day repair returns $800 — more than a decade of premium. On a policy nobody ever uses, it stays a small charge that quietly accumulates.
| Tier | Yearly premium | Per-day limit | Claim ceiling |
|---|---|---|---|
| Basic | $24-$40 | $30/day | $900 |
| Standard | $40-$70 | $40-$50/day | $1,200-$1,500 |
| Enhanced | $70-$96 | $60+/day | $1,500+ |
Ready to compare car insurance rates?
See quotes from top insurers side by side. Free, about two minutes, no obligation.
Get My Quotes →Situations Where Rental Car Reimbursement Coverage Pays Off
The endorsement justifies itself under particular conditions. Buying it makes sense when:
- There is exactly one car in the household and nothing parked behind it.
- No workable transit option exists for the commute, or that drive runs past 30 minutes.
- The car earns money through delivery, rideshare, or similar work, so every idle day has a price.
- The vehicle is older, or wears trim-specific parts with a history of long backorders.
- The garaging address falls in a region with persistent body shop backlogs — coastal Florida once hurricane season ends, sections of Texas after hail, and Southern California more or less always.
- The carrier sells a flexible version that reimburses Uber or Lyft rides instead of a rental agency alone.
Where a second car already sits available in the driveway, that same $60 a year usually does more good in savings.
Less Expensive Ways to Stay Mobile
The endorsement is not the only route to staying on the road during a repair. A few alternatives compete on cost:
- The other driver's liability. When somebody else caused the crash, their property damage liability pays for loss of use — the industry's term for a rental. Their carrier pays you directly, which means your own endorsement duplicates protection that already exists in that situation.
- Benefits built into credit cards. Collision damage waivers on rentals come attached to certain Visa Signature, Mastercard World Elite, and premium travel cards — mostly a travel perk, though a handful stretch to courtesy vehicle benefits after a covered accident. The terms differ sharply from issuer to issuer and card to card.
- A sinking fund earmarked for repairs. Putting away $60 a year over five years leaves $300 — a week or more in a compact rental at 2026 prices.
- Loaner programs from the manufacturer. Lexus, BMW, and Audi are among the brands handing out loaners during covered warranty work. That does nothing for a collision claim, but it is worth knowing before paying for an endorsement.
- Transit passes and rideshare credit. In tightly packed metros such as New York, Chicago, or Boston, a month of transit plus $150 of rideshare credit frequently costs less than two weeks in a rental.
Filing the Claim Without Paying Out of Pocket
Extracting full value takes a few deliberate steps. Before you set foot at a rental counter, get written confirmation from the adjuster on the daily limit, on whether the insurer direct-bills with Enterprise or Hertz (most big carriers do), and on whether taxes fall inside the reimbursement or land on you separately.
Pick a rental class the allowance actually covers. A compact or midsize sedan fits inside a $40-per-day limit; take an SUV or truck at $75 to $100 a day and a shortfall is guaranteed. Counter staff routinely nudge customers toward upgrades, and turning them down is usually correct.
Bring the rental back the day the repair wraps up. Coverage ends at midnight on the completion date, so hanging onto the car over a weekend for convenience creates two or three days you pay yourself. If the shop is the source of the delay, call the adjuster ahead of time; extensions beyond the day cap do get approved sometimes, particularly when the carrier intends to subrogate against the at-fault driver.
Frequently Asked Questions
Does the coverage apply to crashes someone else caused?
It does, and that is precisely where it often turns redundant. When another driver is at fault, their liability policy — the property damage portion that pays loss of use — should be funding the rental directly. Claiming on your own coverage still works, and your carrier will subrogate against theirs, but going straight to the at-fault insurer keeps a claim off your own record.
How long does the coverage typically keep paying?
Most policies stop at either a dollar figure, commonly $900 or $1,500 — or a day count, usually 30. Whichever arrives first ends it. When the car is declared a total loss, most insurers fund the rental only up to the settlement offer — often a mere 3 to 7 days after the appraisal — even though the driver still has to go shopping for a replacement.
Can the daily allowance go toward Uber or Lyft?
More carriers allow it every year — Progressive, State Farm, and Allstate among them — letting policyholders spend the daily allowance on rideshare, taxis, or transit rather than a physical rental. It is not universal, so confirm with your specific insurer before assuming Uber receipts will be honored. Save the receipts regardless, because the adjuster needs them to pay.
Is this the same as the insurance sold when I rent a car?
No. Rental reimbursement funds a temporary car after a covered claim on the vehicle you own. The products people call rental car insurance — damage waivers and liability sold at the airport counter — protect a car you are renting while traveling. A standard auto policy's liability and physical damage protection frequently extends to rentals anyway, which makes the counter offer redundant for a lot of US drivers.
Ready to compare car insurance rates?
See quotes from top insurers side by side. Free, about two minutes, no obligation.
Get My Quotes →